In most car accident cases, the driver who hits another car from behind is automatically considered at fault. This is not just a cultural assumption; it is a legal rule that has been applied in courts for decades. The logic is simple: drivers have a duty to maintain a safe following distance, pay attention to the road ahead, and react in time to avoid a crash. If you rear-end someone, the law presumes you were following too closely, driving too fast, or not paying attention. That makes you the liable party.
But the rule is not absolute. There are specific situations where the driver in front can be held partially or even fully responsible for a rear-end collision. If you have been hit from behind, or if you are the one who caused the rear-end crash, understanding these exceptions can change the outcome of your claim.
The most common defense against a rear-end liability presumption is the sudden or unexpected stop. If the car in front slams on its brakes for no legitimate reason—especially in the middle of a highway or at a green light—the rear driver may argue that the stop was unforeseeable and unavoidable. Courts will look at whether the lead driver’s action was reasonable. For example, if someone brakes hard to avoid a pedestrian who darts into the road, that is a valid emergency stop. The rear driver is still at fault because they should have been able to stop. But if the lead driver brakes because they missed their turn, or because they got distracted by a phone, that sudden stop may shift some blame.
Another key scenario involves defective brake lights. If the lead vehicle’s brake lights are not working, the rear driver may not know the car is slowing down until it is too late. In many states, this can reduce or even eliminate the rear driver’s liability. The lead driver has a legal duty to maintain working lights. If they fail to do so, they contributed to the accident. The same applies if the lead car has no functional taillights at night, making it nearly invisible from behind.
Rollback accidents also complicate fault. If a car is stopped on an incline and rolls backward into the vehicle behind it, the rolling car is at fault. The driver has a duty to keep their foot on the brake. But in some cases, the rear driver may have been stopped too close, leaving no room for a rollback margin. An experienced adjuster will examine the distance between the bumpers and the slope of the road.
Drunk driving or reckless behavior by the lead driver can also overcome the presumption. If the driver ahead is weaving, driving erratically, or suddenly changes lanes and then brakes, the rear-end collision may not be the rear driver’s fault. But you need proof—dashcam footage, witness testimony, or a police report documenting the erratic driving. Without evidence, the insurance company will almost always side with the lead driver.
The most important thing to remember is this: the presumption of fault in rear-end collisions is strong, but it is not a verdict. It is a starting point. To shift liability, you must have clear evidence that the lead driver did something unreasonable. A police report that notes the lead driver’s brake lights were out, or that they admitted to slamming on the brakes for no reason, can be powerful. Eyewitness accounts, skid mark analysis, and vehicle damage patterns also help.
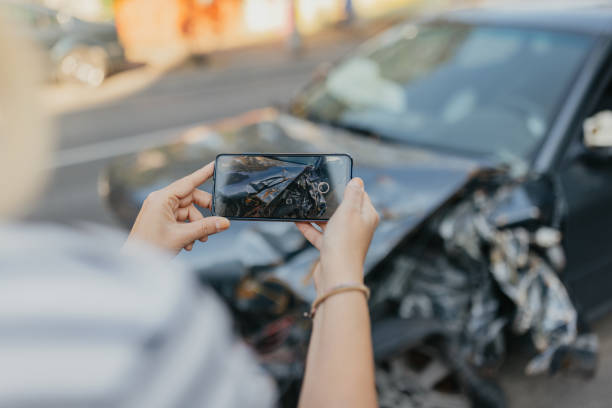
If you are the rear driver, do not admit fault at the scene. Let the police and insurance company investigate. If you are the lead driver, do not assume you are automatically in the clear just because you were hit from behind. Document everything. Take photos of the damage, the road conditions, and especially your own brake lights working after the crash. If possible, get the contact information of any witnesses who saw the other driver speeding or driving erratically before the impact.
Insurance adjusters handle rear-end claims every day. They know the presumption rule and will use it against you if you are the rear driver. But they also know the exceptions. A skilled attorney or a well-prepared claimant can often negotiate a shared-fault settlement instead of a full denial. In some states, if the lead driver is found even 10 percent at fault, that can reduce the rear driver’s payout. In others, like those with pure comparative negligence laws, the rear driver can still recover damages even if they were 99 percent at fault.
The bottom line: rear-end collisions are not always the rear driver’s fault. But you must be ready to prove otherwise. Presumption is not proof. If you have a case, don’t accept a low offer or a denial based solely on the rule of thumb. Fight with facts.