Working with an insurance claims adjuster is the core of getting a liability claim resolved. This person is not your advocate, your friend, or your enemy. They are an employee of the insurance company whose job is to investigate the claim, determine what their policyholder is liable for, and settle the claim for the lowest reasonable amount. Understanding this dynamic is the key to a successful outcome. Your goal is to present a clear, factual, and well-documented case that makes it difficult for them to justify denying or lowballing your claim.
Start by getting the adjuster’s direct contact information and claim number. Every conversation and piece of paper should reference this number. Your first discussion should be factual and brief. Stick to the basic who, what, when, and where. Do not speculate, admit fault, or offer a detailed opinion on injuries or damages. Simply state the facts as you know them. It is wise to let the adjuster know you are documenting your damages and will provide a full package. This sets a professional tone from the beginning.
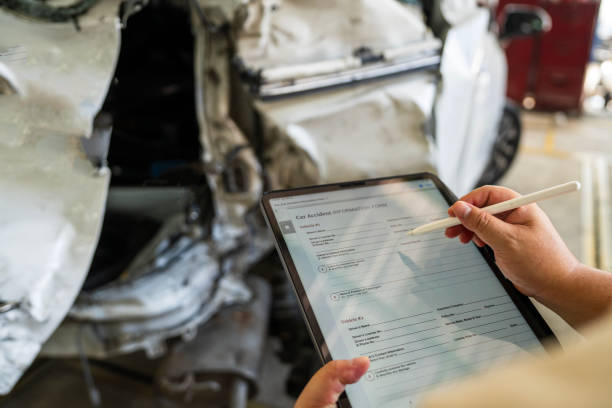
Documentation is your most powerful tool. For property damage, this means photographs, repair estimates, and receipts. For injury claims, this means medical records, bills, and a diary detailing your pain, limitations, and how the incident has affected your daily life and work. Organize this information logically before sending it. Do not dribble documents to the adjuster piecemeal. Sending a complete, organized package forces them to review the full scope of your claim at once and demonstrates you are serious and prepared.
The adjuster will likely request a recorded statement. Be cautious. You are generally not legally required to give one, especially early on. If you choose to provide one, prepare as if for a job interview. Review the facts, keep your answers concise and on topic, and never guess. If you do not know an answer, say so. Remember, anything you say can be used to challenge your claim. It is often safer to decline a recorded statement and instead direct the adjuster to the evidence in your documentation package.
Negotiation is inevitable. The first settlement offer is almost always a starting point, not a final number. Do not react emotionally. Instead, respond in writing. Outline point-by-point, referencing your documentation, why the offer is insufficient. For example, “Your offer of $X for medical bills does not account for the future physical therapy outlined by Dr. Smith in the enclosed report.” This forces a factual counter-argument. Be reasonable but firm. Know the realistic value of your claim, which includes not just past bills but also future costs, pain and suffering, and lost wages.
Throughout this process, keep a log. Note every call with the adjuster’s name, the date, time, and a summary of what was discussed. Follow up important verbal conversations with a brief confirming email. This creates a paper trail and holds everyone accountable. If the adjuster is unresponsive, escalate to their supervisor. Persistence is required. Working with an adjuster is a business transaction. By being prepared, professional, and persistent, you shift the balance of power and significantly increase your chances of a fair settlement.