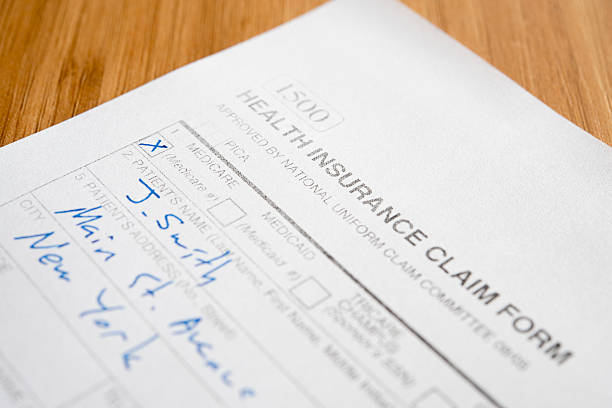
Navigating the relationship with your insurance company can often feel like walking a tightrope. On one hand, you want to be a responsible policyholder and ensure your coverage remains intact. On the other, you fear that reporting too much could lead to increased premiums or even non-renewal. Understanding precisely when and what to report is crucial for maintaining both your financial protection and your peace of mind. The guiding principle is straightforward: you must report any incident that could reasonably lead to a claim, whether you choose to file one immediately or not. However, the application of this principle requires careful consideration of your policy’s terms and the nature of the event.
The most unambiguous scenario requiring immediate reporting is any incident involving significant loss, damage, or liability. This includes major events like a house fire, a serious car accident with injuries or substantial vehicle damage, a burglary, or significant water damage to your home. In these cases, time is of the essence. Prompt reporting allows the insurer to begin their investigation while evidence is fresh, helps mitigate further damage—a duty often outlined in your policy—and accelerates the claims process to get you back on your feet. Furthermore, most policies have explicit clauses requiring notification within a specific timeframe following a loss; failure to do so could jeopardize your coverage for that event.
Beyond these clear-cut catastrophes, the waters become murkier. For instance, in auto insurance, you should generally report any accident involving another driver or vehicle, regardless of how minor it seems. A small fender-bender can escalate if the other party later claims injury. Reporting creates a formal record and allows your insurer to fulfill their duty to defend you. Similarly, for homeowners insurance, you should report any damage that you believe exceeds your deductible and that you would like repaired. If a tree limb falls on your roof, causing a clear breach, reporting is necessary to initiate the repair process under your policy.
However, not every scratch or dent necessitates a call to your insurer. For minor, single-vehicle incidents where the cost of repair is likely only slightly above or even below your deductible, paying out-of-pocket may be more prudent. Filing small claims can label you as a higher-risk policyholder, potentially leading to surcharges that outweigh the claim payout over time. The same logic applies to minor home issues. A small, contained water leak you fix yourself for a few hundred dollars typically does not need reporting. The key is to make a realistic assessment of the repair cost versus your deductible and the potential long-term impact on your premiums.
Crucially, you must also report changes in your circumstances that affect your policy’s risk profile. This is not about filing a claim, but about maintaining accurate coverage. Significant renovations that increase your home’s value, installing a swimming pool, starting a home-based business, or changing your primary address for auto insurance all need to be communicated. Failure to report these material changes can result in denied claims or even policy cancellation for misrepresentation. Conversely, changes that lower your risk, like installing a security system or removing a trampoline, are also worth reporting as they may qualify you for discounts.
When in doubt, the safest course is to contact your agent or insurer for guidance. You can often describe the situation hypothetically without officially filing a claim, asking for advice on whether it meets the threshold for reporting. Document everything meticulously—take photographs, keep receipts, and note down details and conversations. This paper trail is invaluable. Ultimately, insurance is a contract of utmost good faith. By promptly reporting legitimate claims and material changes, while using discretion for minor, self-contained losses, you uphold your end of that contract. This balanced approach ensures your insurer remains your ally in times of genuine need, protecting your assets without unnecessarily inflating your costs over the long term.