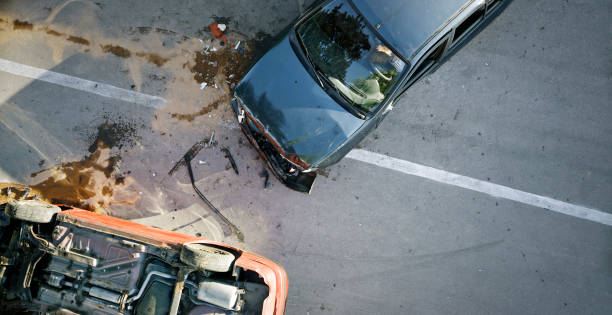
If you get hurt in a car crash, your first thought might be that the other driver pays for everything. That is true a lot of the time, but not always. Many states follow something called comparative fault. That rule can cut your payout, sometimes a lot, based on your own share of blame for the wreck. You need to know how this works before you file a claim or talk to an insurance adjuster. Otherwise, you could end up with far less money than you expected, or nothing at all.
Comparative fault is just a legal way of saying that if you contributed to the accident, you cannot collect the full amount of your damages. Say you were speeding down a highway and another driver ran a red light and hit you. The other driver was definitely at fault for running the light. But you were also breaking the law by speeding. A jury or an insurance adjuster might decide you were twenty percent at fault for making the crash worse. Under comparative fault, your payout gets reduced by that twenty percent. If your medical bills, lost wages, and pain and suffering total one hundred thousand dollars, you would only get eighty thousand.
There are two main versions of comparative fault used across the United States. The most common one is called modified comparative fault. Under that rule, you can recover money only if your share of fault is less than fifty percent. If you are exactly fifty percent at fault, you get nothing in some states, and in others you get nothing if you are fifty-one percent or more. So if a jury says you were fifty-one percent responsible for the crash, the other driver owes you zero. That happens more often than you might think. For example, if you made an illegal left turn and the other driver was texting, the adjuster might argue you caused the danger and you were more at fault than the texter.
The other version is pure comparative fault. Only about a dozen states use it, including California and New York. In a pure comparative fault state, you can collect money even if you were ninety-nine percent at fault. Your payout is simply reduced by your percentage. So if you had one hundred thousand dollars in damages and the jury finds you ninety percent at fault, you get ten thousand dollars. It is a small amount, but it is better than nothing. The insurance company will still try to pin as much fault on you as possible to shrink the payout.
How do insurance adjusters and lawyers decide your percentage of fault? They look at the facts of the crash. Police reports, witness statements, photos, skid marks, and traffic camera footage all come into play. They also consider whether you were following the basic rules of the road. Things like failing to signal, driving too fast for conditions, running a stop sign, or even being distracted by your phone can all count against you. In some cases, your own actions before the crash matter too. If you knew your brakes were bad but drove anyway, or if you had been drinking, that will increase your share of fault.
Comparative fault does not apply only to car accidents. It also comes up in other bodily injury claims, like when a contractor works on your property and you get hurt. For instance, if a contractor leaves a ladder unsecured and you climb it despite knowing it is wobbly, a court might find you partially at fault for your own injury. That reduces the amount the contractor has to pay you. The same reasoning applies to slip-and-fall cases, product liability incidents, and even medical malpractice.
The key takeaway is that you cannot assume the other party will pay every dollar of your losses. Comparative fault is a powerful defense that insurance companies use every day. If you were doing anything wrong at the time of the accident, even something small, expect the adjuster to argue that you share the blame. That is why you need to be honest with your lawyer about everything you did before, during, and right after the crash. Small details you think are harmless can turn into big percentage points against you. And if you live in a modified comparative fault state, a few percentage points can mean the difference between a settlement and a zero payout.
If you are thinking about handling your own claim, be very careful. Insurance adjusters are trained to gather evidence that shows you were partly at fault. They will ask questions designed to get you to admit you were distracted, driving too fast, or not paying attention. Anything you say can be used to reduce your claim. A good personal injury lawyer knows how to counter those tactics and argue for the lowest possible percentage of fault on your side. In many cases, a lawyer can also find evidence that shifts more blame onto the other driver, which increases your payout.
Comparative fault is not something you can ignore. It is a reality in almost every state. Understanding how it works helps you make smart decisions after an accident. Do not sign anything or accept a quick settlement before you know how much fault you might be assigned. A small check now could be far less than what you deserve once your true share of fault is calculated. Get the facts first, then decide.