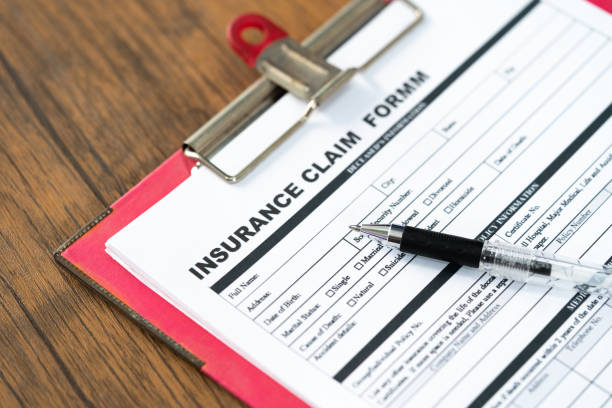
Submitting a formal claim form is the critical, non-negotiable step that turns an accident into a process an insurance company must handle. This is not a casual conversation or an email summary. It is the official start of your financial recovery, and doing it correctly removes excuses for delay. The goal is to be clear, complete, and undeniable, forcing the adjuster to see the facts as you present them.
Begin by getting the correct form. Do not write a letter and call it a claim form. Contact the insurance company directly—the one for the at-fault party or your own, depending on your situation—and request their official “Proof of Loss” or “First Notice of Loss” form. If they direct you to a website to download it, do so. Using their document ensures you provide the information their system is designed to process. Before you write a single word, make a complete copy of the blank form. You will use this as your working draft.
Your job when filling it out is to become a relentless fact-collector. Every field demands a precise answer. For personal information, use your full legal name and a reliable, monitored address and phone number. In describing the incident, strip away all emotion, opinion, and speculation. State only the objective facts: the date, time, exact location, and a concise sequence of events. Use plain language like “the driver of the blue sedan failed to stop at the red light and struck the front passenger side of my vehicle” rather than “he recklessly slammed into me.“ Attach a separate page if you need more space, but label it clearly.
The sections on damages and injuries are where detail is paramount. For property damage, list every single item affected. If it’s a car, you will need a repair estimate from a licensed shop. If it’s personal belongings, list each one with its age, purchase price if known, and a description of the damage. For injuries, list every ache, cut, and bruise. You must include the full names and addresses of all treating medical providers, from the ambulance service to your primary doctor. This creates a paper trail the insurer cannot ignore. Do not guess at future costs; state what you have incurred so far and note that treatment is ongoing.
Gather your supporting documents before you even look at the form. This includes the police report, all medical bills and records, repair estimates, photos of the damage, and proof of lost wages from your employer. Number each document. When the form asks for supporting evidence, you will create a “Schedule of Attachments” listing each item by number and description. This organizes your claim into an undeniable package. Keep the originals of everything. Send only photocopies or scanned duplicates with your form.
Finally, submit the claim form and its entire attachment package using a method that provides proof of delivery and a date stamp. Certified mail with a return receipt or a tracked courier service is the standard. An online portal is acceptable only if you receive a clear confirmation and reference number. Keep this proof with your claim file. The clock on the insurer’s obligation to respond starts the moment they receive this package. You have now done your part: you have formally forced the issue onto their desk, presented with clarity and evidence, and removed ambiguity. The burden to act next is squarely on them.